Omar, the founder of ML LABS, spends 90% less time on his own investing than before. ML LABS applied its own engineering to his personal portfolio and built a prototype that manages it every day. Within the first days of use, ROI rose 50%. His risk measures improved too: the Sharpe ratio rose and Value at Risk fell, with no drop in expected return.
This is Omar's own money. It is not client money, and these are not results of CVEST.ai, the product now in development. The prototype is what CVEST.ai grew from, and CVEST.ai is built for retail investors who want better tools for their own money, not for a professional trading desk. The prototype showed what such a tool can do for one person.
Investing Time Cut By 90%
- Time spent on investment activities fell by 90%.
- ROI rose 50% within the first days of use.
- The Sharpe ratio rose and Value at Risk fell, with no drop in expected return.
- The prototype now manages the portfolio automatically, every day.
These are results on one personal portfolio, and past results do not guarantee future results.
Before the prototype, running the portfolio meant the same routine most individual investors know. Omar gathered prices and positions, checked each holding against his plan, decided what to change, placed the trades and then worked out where the portfolio stood. Each step took his attention, and the steps repeated whenever the market moved. The prototype took over that routine, and his time now goes to the decisions only he can make.
Strategy Holes Found In Days
The ROI gain came from what the prototype found in the strategy itself. It checked Omar's rules against his actual positions and pointed out holes in the strategy, places where the portfolio did not do what the plan said it should. It also suggested more efficient ways to execute trades. Together, those changes raised ROI by 50% within the first days of use.
A strategy can be sound on paper and still lose value in execution. The gap between paper and actual returns (Journal of Portfolio Management, 1988) is the implementation shortfall, the cost of turning decisions into trades. An individual investor rarely measures it, because nothing in the usual routine makes it visible. A system that checks every rule and every trade does, and the holes stop costing money the day they are found.
The strategy was already written down. What changed was that a system now checked it, every single day, against the real portfolio he holds.
Sharpe Ratio Up, Value At Risk Down
Return is only half of a result; the other half is the risk taken to get it. Two standard measures describe it. Return per unit of risk (Journal of Portfolio Management, 1994), the Sharpe ratio, is better when it is higher. The loss a portfolio could plausibly suffer (Financial Analysts Journal, 1996) over a set period, Value at Risk, is better when it is lower.
On Omar's portfolio, both moved the right way. The Sharpe ratio rose and Value at Risk fell, and expected return did not drop. Lower risk usually costs expected return, which is why the pair matters: the portfolio became safer without giving up what it was expected to earn.
A Portfolio Managed Every Day
The prototype runs the same loop every day, whether or not Omar looks at it. It reads the portfolio and market data, checks the positions against the strategy, proposes the trades that bring them back in line, executes them, and reports the resulting risk.
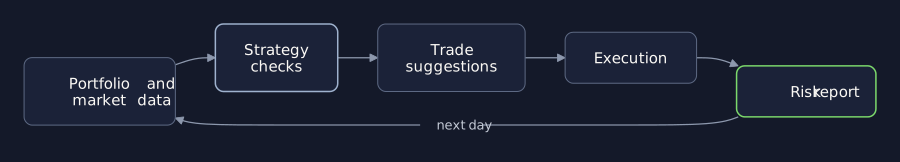
Because the loop runs daily, a gap between the plan and the portfolio is caught the next day, not the next time someone has a free evening. The risk report closes each cycle, so the portfolio's state is read, not reconstructed. Individual investors who trade most (Journal of Finance, 2000) earned the lowest net returns in a sample of household accounts. A disciplined loop trades when the strategy calls for it, not when attention happens to be free.
Built For Retail Investors
CVEST.ai takes what the prototype proved and builds it for retail investors: people managing their own money who want better tools. It is not software designed around a professional trading desk, with its staff and data feeds. It is for one person at one desk who wants their strategy checked, their trades executed efficiently and their risk measured every day.
The prototype and the product are separate. The prototype's results come from one personal portfolio, and CVEST.ai will be measured on its own. What carries over is the engineering: the daily loop, checks against a written strategy, and a risk report closing every cycle.
Same Engineering For Your Work
ML LABS took a routine that consumed hours, broke it into steps a system can run, and kept the person on the decisions that need judgment. That is the same work it does for companies: find the process that eats attention, check it against the rules it should follow, and let a system run it every day, with a clear record of each step.
If one of your processes still depends on someone assembling data, checking it by hand and acting on it, a first call is where to map it and see what a daily loop would change.
References
- Perold, A. F. The Implementation Shortfall: Paper Versus Reality. Journal of Portfolio Management, 1988.
- Sharpe, W. F. The Sharpe Ratio. Journal of Portfolio Management, 1994.
- Jorion, P. Risk2: Measuring the Risk in Value at Risk. Financial Analysts Journal, 1996.
- Barber, B. M., & Odean, T. Trading Is Hazardous to Your Wealth. Journal of Finance, 2000.